Showing posts with label Interchange. Show all posts

Friday, November 25, 2016

Interchange Plus Benefits and Cost Savings

How Interchange Plus Saves Money When the Markup Becomes Too Expensive

When you have a business, whether it is a retail store, grocery cart or lawncare service, you have to be able to take payments. In today’s world, this means being able to take credit cards easily. Most of your customers are not likely to have cash or even a check on hand to make a payment for products or services. You must be ready to fulfill their need and accept a form of payment that is convenient for them. However, accepting credit cards comes with its own issues, like fees. How do you best handle these fees? Many businesses are finding that interchange plus is a solution to this problem.

What Is Interchange Plus?

Typically, you will have a few options on how your fees will be structured for credit card payments. Common options include bundled or tiered pricing. Interchange plus is another option. With this, you get a pricing structure that allows you to see the components of the costs. It is reported much more clearly and allows you to plan your costs much more easily. It is available for Visa, MasterCard and Discover. 

How Does It Work?

When you process a credit card, the credit card brand will set an interchange rate that you are charged for this transaction. You are also charged a processing fee by the processor. The amount of what you are charged for processing can vary by industry. 

How interchange plus works is it allows you to see the basic processing fees and interchange fees individually instead of bunching them into one basic fee, which is how other methods do it. It allows you to see exactly what you are being charged for every transaction, so you can optimize your credit card related expenses. This is compared to other systems that lump everything together so you do not get to see what is being charged where, so you may never really know what processing or interchange fees you are paying.

What Are the Benefits?

The main benefit here is that it is clearer than other options. You get to see what you are paying in a very easy to understand format. Because you are able to see all the fees, this opens doors to getting lower fees. Companies are more willing to lower costs, which passes the savings onto your business. In addition, you can better choose a processing company because you will know what they are charging you and immediately see the best offer. 

How Do I Find the Best Deal?

The rates you are offered can vary quite a bit. They are based upon many different factors. So, what may be great rates for one business may not be for another. You have to consider things like what industry you are in, how much risk your business poses and your average transaction amounts. There really is no one answer to the question of what is the best deal. The best thing you can do is choose a processing company that has your best interests in mind and who is willing to work with you. They should be open to the idea of interchange plus, too. If a company is used to this method, it will often be very happy to offer you the best possible rates. 


This guest post by Brian Thompson has been provided by our friends at Transaction Services.
Brian Thompson is a business man who means business.  He has helped several companies thrive in the business world, and in his spare time writes for several blogs.
Follow him on Twitter @Biz_Gab

Friday, October 16, 2015

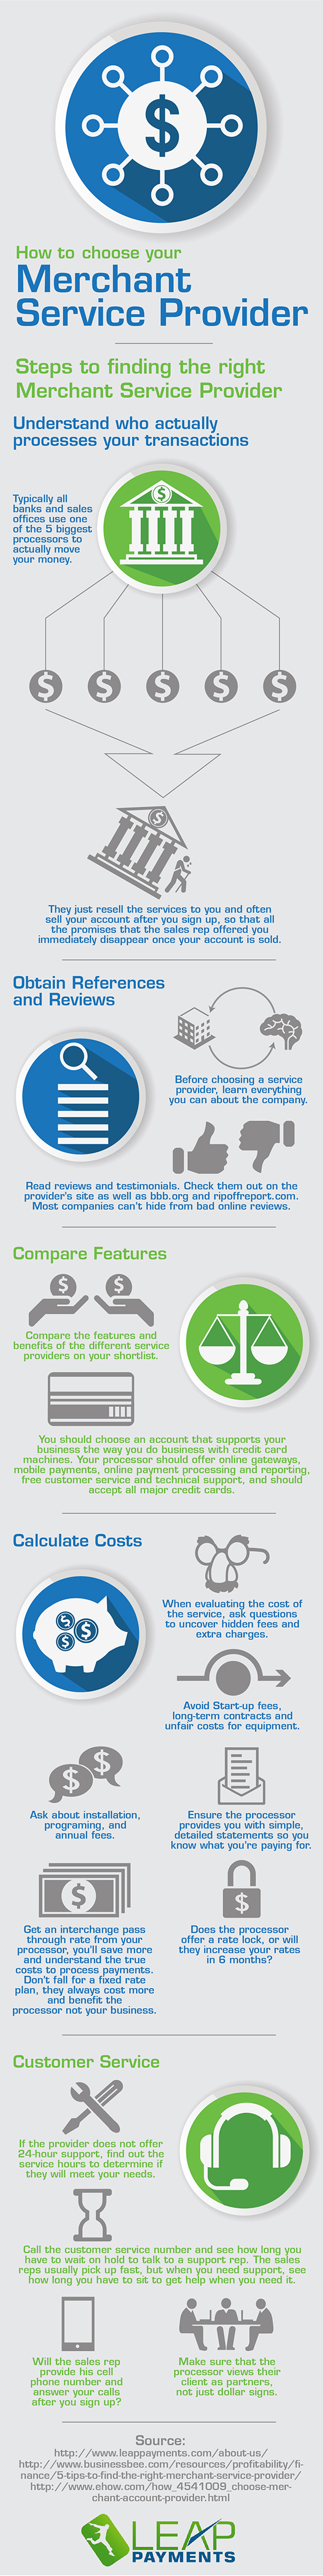
How To Choose Your Merchant Services Provider

Below is an infographic provided by Leappayments.com -- they contacted me a long, long time ago about featuring this on my blog and it managed to get lost in my inbox for quite a while. Every now and again, I would pull it up and look at it and think to myself that, yes, it was a nice infographic.

And since it features information that, for the most part, I have already written about in various posts, I thought this might act as a handy reminder. So, here it is, compliments of Leap Payments, with whom I have no working relationship, and therefore cannot vouch for the company beyond this excellent presentation.

I will caution only one thing with regard to the infographic. It suggests that you pay attention to online reviews, which you should -- but it does not go into detail about how a very small number of rather loud or disgruntled merchants might give very bad reviews of a company that are because of situations where the merchant was at fault. I've read enough such reviews to be able to recognize them, but most merchants and potential agents probably have not. Trusting bad reviews or outstanding reviews blindly is not a good thing -- always look for reviews that give a balanced view of the experience, back up the conclusion with good examples and otherwise tell something more about the company. Neither a few bad reviews nor a few good ones are likely to tell an accurate picture of a company. Additionally, negative reviews (especially on Rip Off Report) are much more common than positive reviews overall, because people having a good experience are less likely to feel the need to write a review in the first place. After all, why would anyone go out of their way to say, "Company X is doing exactly what they are paid to do," which is essentially what every good review would be saying. It's a service, people! Expect it to work properly and be a good value for the money!


Tuesday, September 22, 2015

Here is a useful guide to the essentially current Interchange Rates for those of you looking to assess actual hard costs of processing. Keep in mind that the rates do fluctuate several times per year, and that these are the hard costs from the card brands themselves, not including the costs of processing as added by the actual processor or bank you are doing business with (either in the form of markup percentages, fees or a combination of some sort).


For a complete list of US interchange rates, please visit the Visa and MasterCard websites below:
http://usa.visa.com/download/merchants/Visa-USA-Interchange-Reimbursement-Fees-2015-April-18.pdf

http://www.mastercard.com/us/merchant/pdf/MasterCard_Interchange_Rates_and_Criteria.pdf


Current Interchange Rates in the United States


Visa Debit MasterCard Debit
Debit Retail Swipe


Debit Retail Swipe


Visa Debit CPS 0.800 % + 15¢ MC Debit 1.050 % + 15¢
Visa Debit CPS Regulated 0.050 % + 22¢ MC Debit Regulated 0.050 % + 22¢
Visa Debit Prepaid 1.150 % + 15¢ MC Debit Prepaid 1.050 % + 15¢
Visa Debit Business 1.650 % + 15¢
Visa Debit Business Regulated 0.050 % + 22¢


Debit Keyed

Debit Keyed
Visa Debit Keyed CPS 1.650 % + 15¢ MC Debit Keyed 1.600 % + 15¢
Visa Debit Keyed CPS Regulated 0.050 % + 22¢ MC Debit Keyed Regulated 0.050 % + 22¢
Visa Debit Keyed Prepaid 1.750 % + 20¢ MC Debit Keyed Prepaid 1.760 % + 20¢
Visa Debit Keyed Business 2.450 % + 10¢
Visa Debit Keyed Business Regulated 0.050 % + 22¢


Visa Credit Retail Swipe
MasterCard Credit Retail Swipe

Visa CPS Retail 1.510 % + 10¢ MC Consumer 1.580 % + 10¢
Visa Rewards Traditional 1.650 % + 10¢ MC Enhanced 1.730 % + 10¢
Visa Rewards Signature 2.300 % + 10¢ MC World 1.770 % + 10¢
Visa Rewards Signature Preferred 2.100 % + 10¢ MC World Elite 2.300 % + 10¢
Visa Corporate 2.100 % + 10¢ MC Corporate 1.900 % + 10¢
Visa Business 2.200 % + 10¢
Visa Purchasing 2.400 % + 10¢


Visa Keyed


MasterCard Keyed
Visa Keyed CPS Retail 1.800 % + 10¢ MC Keyed Consumer 1.890 % + 10¢
Visa Keyed Rewards Traditional 1.950 % + 10¢ MC Keyed Enhanced 2.040 % + 10¢
Visa Keyed Rewards Signature 2.700 % + 10¢ MC Keyed World 2.050 % + 10¢
Visa Keyed Rewards Signature Preferred 2.300 % + 10¢ MC Keyed World Elite 2.950 % + 10¢
Visa Keyed Corporate 2.950 % + 10¢ MC Keyed Corporate 2.650 % + 10¢
Visa Keyed Business 2.950 % + 20¢
Visa Keyed Purchasing 2.950 % + 10¢
Real Estate & Property Management
MC Real Estate Consumer 1.100 %
MC Real Estate Enhanced 1.100 %
MC Real Estate World 1.100 %
MC Real Estate World Elite 2.200 %
MC Real Estate Corporate 2.650 % + 10¢
Charities
MC Charity Debit (non-regulated) 1.450 % + 15¢
MC Charity Credit 2.000 % + 10¢
International International
Visa International 1.100 % MC International 1.100 %
Visa International Premium 1.100 % MC International Keyed 1.600 %
Visa International Corporate 2.000 %
Visa International Keyed 1.600 %

Association Fees

Association Fees

Visa Card-Brand 0.1300 % MC Card-Brand (Under $1000) 0.1100 %
Visa NAPF (Network Acquirer Processing Fee) 1.95¢ MC Card-Brand (Over $1000) 0.1300 %
Visa Clearing Access 0.25¢ MC ALF (Acquirer License Fee) 0.0045 %
MC NABU (Network Brand Usage Fee) 0.185¢
MC Account Status Inquiry (on $0 auth) 2.500¢
Visa International Cross-Border 0.8000 % MC CVC 2 Authorization Fee 0.250¢
Visa Intl Acquirer Service Fee 0.4500 % MC AVS Authorization Fee 1.000¢
Visa FANF (Fixed Acquirer Network Fee) MasterCard Intl Cross-Border Support 0.4000 %
Visa FANF - Card-Present Per Location $2/mth MasterCard International Cross-Border 0.8500 %
Visa FANF - Keyed Volume $1,000 - $3,999 $7/mth
Visa FANF - Keyed Volume $4,000 - $7,999 $9/mth
Visa FANF - Keyed Volume $8,000 - $39,999 $15/mth
Visa FANF - Keyed Volume $40,000 - $199,999 $45/mth

Thursday, July 10, 2014

Affordable Tablet POS Systems That Support Open Checks and Tips from Groovv and ShopKeep POS

Android and iOS based POS Systems perfect for small and mid-size restaurants, coffee shops, bars or any business that accepts tips or open tabs.

Most mobile credit card processing solutions are not able to handle tips or open checks (tabs) at all, acting strictly as the equivalent of a counter-top terminal for swiping or key-entering a single transaction. This works well enough for most people, who rarely will need modifiers of any sort. However, business owners wishing to move away from or avoid altogether the high-priced POS systems now are seeing viable options appear in the affordable tablet-based solutions entering the market.

While affordable solutions such as Harbortouch have begun presenting themselves in the market for full POS systems required for high-inventory merchants who need extensive employee tracking and reporting for the accountant, the mobile marketplace has seen an explosion recently with excellent retail solutions like

Sunday, April 6, 2014

Time Again for Increases in Interchange Costs

April Interchange Increases

It happens at least twice each year: the credit card processing companies all send out notices regarding unavoidable pricing increases for their merchants. Like clockwork, April brings the news, usually overlooked by merchants who are used to glancing past the fine print on their monthly statements (if they read them at all). In case you missed it, here is a brief rundown of some current increases in interchange cost associated with the major credit card brands.

Not surprisingly, processing companies use this excuse to cry poor, and in addition to merely passing the additional costs on to merchants, they will mostly tack on across the board increases to compensate for the new expenses while also generating more income.

Monday, March 10, 2014

New PayAnywhere (Free) Tablet Storefront Solution Is Here

First the good news: North American Bancard (NAB) has a new PayAnywhere branded mobile tablet-based processing program which offers the placement of a free counter-top system and some great new options built around a 10 inch Android tablet (plus an additional mobile card reader for phones or tablets). It is one of the most affordable processing solutions on the market that takes advantage of mobile solutions at highly competitive rates with a future-ready, upgradable combination of hardware and software. It will become EMV compliant and is consistently being updated on the software side to take advantage of the latest technology while offering more enhancements to merchants. The program is very similar to the previous Phone Swipe Tablet Program which NAB been providing, but without the high volume requirements.

Processing of Visa, MasterCard, Discover, American Express and the new PayPal card are all available with Next Day Funding and a lower swiped rate than Square or any "Pay As You Go" style programs, and still without additional transaction fees.

Having stated the good news, you might expect that there is bad news to counter it. But there isn't, at least not in the sense of anything new about the processing industry. Instead, there is the caveat that merchants still must deal with the same basic pricing and service of typical merchant accounts, including the PCI responsibilities and standard fees. Moreover, however, this program is not a "one size fits all" solution. If merchants are not processing over $5,000 in monthly charges, there is a good chance this program is not for them. On the other hand, it could save the right merchants a lot of money, offer a forward-thinking alternative to standard terminals and increase both productivity and profits. All will be revealed after the jump...

Friday, January 3, 2014

New Phone Swipe Promo, What It Really Means

North American Bancard just released a new promotional push for its Phone Swipe product, touting it as a new, first of its kind deal for 2014. The text of the promo reads:    

"This January, be the first in the industry to offer Visa, MasterCard, Discover and even AMEX at 2.69% with next day funding to all pay-as-you-go customers! It's just another reason why Phone Swipe is the mobile payments solution that sells itself!"  

Since the next day funding option has been standard for new accounts since mid-2013, and since American Express cards have been processing on Pay-As-You-Go accounts at the same qualified rate as Visa, MasterCard and Discover for the same period, I wanted to find out which part of this was supposed to be new for the new year. Well, it turns out that it isn't new and nothing has actually changed in the program. The spin is simply the suggestion that agents should take time now - in January - to point out that Phone Swipe is the first processor to offer qualified charges for the main card carriers at this rate. Agents and merchants should still be aware that the same mid/non-qualified downgrade of 80 basis points continues to apply to all accounts on the Pay-As-You-Go plan, along with the $0.19 transaction fee for business signature cards and even rewards cards.

Does this make the Phone Swipe program a bad deal?


If you have read this blog before, you know that I have endorsed Phone Swipe for a long time. I even

Monday, November 4, 2013

October 2013 Interchange Adjustments

October is typically a month when new pricing adjustments occur in the merchant processing business. The credit and debit card brands, specifically Visa, MasterCard and Discover, make adjustments to their pricing structures and/or services. Once this occurs, the merchant processing companies then generally restructure some of their pricing to prevent profit loss, spread out new costs or otherwise either stay competitive or profitable. Some account managers will choose to absorb certain costs or prevent some merchants from seeing increases in their billing, however it is also possible that some of these posted increases will be used as an excuse to increase fees across the board and not simply for the actual items affected. For this reason, it is always important to read the fine print, or at least the monthly announcements on each processing statement.

Here is a quick breakdown of the recent changes from October, 2013, effective from the beginning of the month. The changes may look small at first, but remember that these tiny amounts add up when they are per transaction. For the card issuing companies, this can mean a huge increase in revenue (although, to be fair, theoretically the increases are designed to deal with corresponding costs already being incurred).

The New Costs

All Discover transactions now have

Sunday, September 22, 2013

PCI Program Update for North American Bancard Merchants

A notice came out today, September 17th, 2013, from the folks over at North American Bancard, which also provides the Phone Swipe and PayAnywhere products in the mobile processing field. Merchants who are on the mobile "Pay As You Go" plan (also known as Option B for Phone Swipe) should note that this information will not apply directly to their accounts, since those types of accounts have the compliance fees rolled into their higher percentage along with all other incidental costs (which is why Phone Swipe may be so much more cost-effective for merchants who do under $2,500 per month).

Here is an excerpt from the NAB correspondance:

"The monthly fee for PCI non-compliant merchants will be increasing from $6.95 to $14.95. This increase is effective for Global merchants and for First Data merchants. Your merchants will continue to receive messages on their statements notifying them when PCI billing will occur.

Note that the annual PCI compliance-related fees will not be increasing. Those fees will remain the same as they have for the past three years: $79 for all main accounts ($99 if non-compliant) and $19.95 for each additional account with the same Tax ID number and/or same Principal/Social Security Number ($24.95 if non-compliant). We are proud to say that these annual fees continue to be lower than those of our top competitors despite the fact that our compliance programs offer significantly better levels of protection and that our costs for the programs continue to increase."

NAB, just like most payment processors, sends their merchants notices regarding Payment Card Industry security standards and compliance issues in the merchants' monthly processing statements. Frequently merchants forget to check their statements for these announcements, which may also include rate or fee increases due to higher percentages being charged by Visa, MasterCard or Discover, that the processor might pass along to the merchant. It is essential that merchants remember to check their monthly statements, not only to verify that they are not being overcharged or billed for something that they do not understand, but to ensure that they are up to date on any changes or responsibilities regarding their accounts.

Wednesday, July 31, 2013

Harbortouch "Free" POS System Program, Simplified

I recently had the opportunity to expand my consulting service with the products offered by Harbortouch, aka United Bank Card, Inc. (UBC). UBC is a very similar company to the other processors I use, in terms of size and offerings and the flexibility of pricing, so there was little incentive for me to go through the paperwork until I looked deeper into their Point of Sale terminal program. As it happened, I had a client who was looking for a POS system and we decided to do some number crunching and some feature comparisons. What we found surprised me.   


My first impression was that the Harbortouch program would probably fall into the "too good to be true" category. Everyone who has been around the block knows that "free" terminals generally means that you get to borrow the equipment if your pricing structure is high enough. That's fine for most businesses, because the minimum pricing requirements to qualify for equipment placement are usually offset by the savings of not having to purchase new equipment combined with the ability to exchange a defective or outdated machine at little or no cost. The one thing that often does get merchants with equipment placement is that they are likely (but not always) locked into a 3-year term with a cancellation fee that is higher than the price of a terminal. But here we are talking about standard counter-top card swiping terminals and nothing beyond that. When moving into POS territory, things become a bit more complicated. And, in this case, more enticing.

Thursday, April 18, 2013

Recommended Solutions


One Size Does Not Fit All

One of the most important things for merchants to remember is that what works best for one business may not be a good fit for another. This applies in almost every area of business, and the processing set up for a business is no different. Except in one way: every merchant wants the cheapest solution that will serve their needs.

The problem is, what saves one merchant money may not save another merchant who does business very differently. Having the lowest transaction fees is terrific until it means that all transactions are going to have to be stored for later because a merchant is trying to save on mobile processing fees, only to discover that more charges are downgraded and other charges are simply not approved... In fact, there are dozens of considerations to be made before ensuring that the merchant has the best program set up.

Some generalizations remain true

It is always in the best interest of a merchant to save money. The rates and fees set by Visa, MasterCard, Discover, American Express, et al,  are varied by card type and transaction type, and even have built in adjustments by industry. There are ways in which the processing companies have worked to save merchants on some types of charges while profiting off other types of charges. This was the birth of "Tiered" pricing.

A good "Tiered" deal may actually save a merchant money over an Interchange-based plan. This may be the case when the Mid- and Non-Qualified markups are not excessively high and the Qualified rate itself is low, because many cards may be processed at very little profit or even at a loss for the processing company, versus the consistent markup on every charge as processed via an Interchange-plus agreement. These kinds of "Tiered" plans are pretty rare, however, and many merchants find that their "Tiered" rates are raised periodically to compensate for the increase in Interchange costs for a few card types every six months or so. This is also assuming that the Interchange-plus plan is based on the typical "book rates" from most processors (likely 50 basis points over cost).

I generally believe that Interchange-based plans are the most fair-minded and often the most cost-effective. There is no undue rounding up on rates, no downgrading. And there is usually no additional transaction fee to go along with the downgrades, either. A merchant pays the cost of processing with a nominal surcharge on the total and a reasonable fee per transaction. This "cuts the fat" and makes the costs much more equitable most of the time. Still, this sort of plan sometimes looks complicated and does not work best for every merchant, so the pros and cons must be examined.

Recommended Solutions

I like to put my merchant clients into a narrow range of solutions whenever possible. For some, they have an existing POS system that needs to be reprogrammed and it is as simple as discovering what processing company will interface best with the POS system and then setting an account up with the proper parameters and lowest available cost. I'll use the First Data network for most POS systems, because I can provide that through a third party at much less than First Data usually charges merchants who have accounts directly set up through their processing wing. Plus, I'll do it with no long-term contracts and without cancellation fees. I can also process over the Global Payments network, or through a gateway like Authorize.net. For most high volume businesses, this sort of solution is perfect for them. They have the hardware already, I'll simply provide them with better numbers. I'm not precisely in the POS business, but I have the ability to set up several types of systems and can provide a limited range of them as well.

Tuesday, September 18, 2012

Why a Merchant Should Never Pay Over 4% in Total Processing Costs

How to spot a bad processing deal 101

It's true: I've spoken with merchants who thought that they were paying a fair price on their processing service even though the aggregate total they were spending for a month of processing was coming out in the range of 5 to 7%. That's right, because they had been with the same service for years and it was provided by a "reputable" company (or even their own bank), these merchants assumed that they were paying market rates and not getting ripped off. But they were wrong.

One of my clients, a plumber, had been paying over 7% when the "discount" rates and transaction fees and monthly fees had all been added together. When he told me this I responded that I was sure he must be mistaken, that no legitimate company should be setting him up at rates that high for his business. But there were his statements, clear as day, and he had been with this same processor for over a decade, just handing the company his hard-earned cash.

All a merchant has to do is check their bottom line. If your total costs to process exceed 4% for any given month and you swipe cards in a retail environment, you have a bad processing deal. Period. Go ahead and figure in the cost of PCI compliance, too. If you're still over 4%, there is a better option on the market. Even if a merchant is primarily processing keyed-in transactions via the Internet, phone or mail order, the total costs should normally be under 4% as well. (Because of some additional costs to process through gateways or shopping carts online, those expenses may need to be removed from this discussion. However, many businesses do spend much more than necessary on gateway fees, so those ought to be examined carefully as part of the bottom line.)

Wednesday, May 23, 2012

What Should Make A Merchant Want To Change Processing Companies?

Merchants must ask themselves why they would consider changing their processor. Perhaps even before the next sales representative walks through their door, seeking their business, it would be a good plan to have the answer in place

Nobody likes wasting their time

As an agent in the field, I can assure any merchant out there that nobody in a sales position enjoys wasting their time. If a sales rep is going to put in the effort to sign a merchant, he or she is going to appreciate knowing the merchant's actual wants and needs. And the merchant will save both time and money by being aware of his or her own expectations. In actuality, if the agent is honest and the merchant is above board, both are on the same side. Many merchants feel adversarial toward sales reps of any stripe, often with good reason. Being on the same page, however, is a win for both the merchant and the rep. The rep may not see the huge profit or windfall initially hoped for, but the relationship should be much more solid and the retention of the client much more likely.

Top Reasons To Consider Switching Credit Card Processors

Consider this check list as a starter only. Every merchant will have different issues that they want to consider and different values attached to each. What ranks as most important to one merchant (i.e., cost savings or next day funding) may be of little importance to another. And it may be that if a merchant has ten things on the list, one or two of them might be flexible options if the other 8 or 9 are going to be handled well.

Thursday, May 17, 2012

Should Sales Reps Be Trusted? Four Ways To Spot A Lie.

Just for the record, most of the time it is probably not in a merchant's best interest to automatically trust a merchant services sales rep. I'm throwing it out there based on my personal experience interacting with both people within the processing companies and the merchants I've met through daily interaction. This isn't to say that sales reps are mostly untrustworthy, but they should earn a merchant's trust and in this industry that is not always easy.

How to spot a lie from a merchant services agent

To be fair, I honestly believe that many sales reps in the merchant services industry are simply ignorant with regard to what they are selling. I've been on that end of a claim, though not for long. In fact, the first "Team Leader" that I worked with used to tell me that I was too smart to be a salesman because I kept talking business owners out of the deal. My question to him was always the same, "aren't we here to save the merchant money?" And Team Leader's answer was always this: "what's important is that the merchant believes he is saving money. We want happy merchants."

Maybe it's just me, but I am happiest when I know I've been treated with honesty and integrity. I am mighty unhappy when I have the sudden realization of having been "sold a bill of goods." And I never wanted any of the merchants I worked with to feel that way, either. Besides, I wanted to provide services to businesses that I actually patronized, that thrived in my own neighborhood. If I set these places up with bad service agreements it would be plenty difficult to show my face out on the street.

Lie #1: I can't quote you a rate

Whenever a sales rep is in a business establishment, he will be quite anxious to find out the current rates that a business is being assessed. This is the crux of the business pitch. A big gasp will generally ensue upon examining a statement, perhaps even some eye rolling or head slapping. It's simply amazing how high those rates are! But what rate am I offering? Oh, I can't tell you that without examining your processing statements first.

Really?

Wednesday, May 16, 2012

When Does It Make Sense To Switch Credit Card Processors?

As a field sales rep in the credit card processing industry, it is important to understand when it is really in a merchant's best interest to switch processing companies. It is even more important for the merchant to be aware of when it is the proper choice. Let's be honest, a sales rep wants the merchant's business. The merchant should simply want what is best for his or her bottom line.

Fear of Change

Most merchants suffer from the same basic phobia with regard to anything involving their banking situation. "If it ain't broke, don't fix it" seems to sum up the excuse for retaining the status quo. To a certain extent, this is reasonable thinking. Functioning processing that gets funds deposited where they are supposed to be is the primary concern of many merchants. A processor that has done this for some time is a known commodity and therefore is also in the merchant's comfort zone. This does not  necessarily mean it is the correct option for the merchant.

When deciding whether to make a change away from a company that has been successfully processing on behalf of a merchant, there are always a few considerations:
  • Contractual obligations or cancellation fees
  • Ease of transition
  • Guarantee of rates and fees
  • Terminal purchase, lease or rental
  • Reprogramming time requirements
  • Customer loyalty or working relationships
  • Fair treatment
  • Company perception
  • Trust
And the list really can keep growing quite easily.