Showing posts with label Merchant Services Companies. Show all posts

Friday, April 7, 2017

Security Threats Facing Online Payment Gateways


[Guest Post by Arthur Jones]
Most experts agree: it is a brave new world for payment gateway providers, which presents both opportunities and challenges. For nearly a decade, cyber security professionals have been warning about the ongoing rise of cybercrime. Agencies like the FBI regularly put out reports detailing the threats to the financial services industry, in particular. As outlets like TechRepublic have reported, this trend is only going to continue, and we may see record levels of cybercrime activity this year.
What kind of threats can we expect to face for online payment gateways? Let’s look at some major security challenges and how they may be addressed payment gateway providers as they continue to innovate and remain competitive in the marketplace.
Information Attacks
It is safe to say that a data breach is one of the most serious threats for payment gateways. Attacks like these can come in many different forms, and because they are smaller and require fewer resources, they are easier to carry out and occur much more frequently. If an attacker gets their hands on sensitive financial information, the losses can be catastrophic, putting companies at the risk of irreparable damage to customer trust.
There are many ways for attackers to breach a system. Phishing attacks consist of fake emails that can trick users into opening harmful links and installing malware or giving up sensitive information. Such attacks can open up system vulnerabilities, giving attackers access to valuable information.
Untrustworthy insiders can also get access to sensitive information and compromise security systems from within the business. Or hackers can gain access to sensitive systems through security breaches in compromised hardware and software.
Credit Card Fraud
Payment gateway providers may be concerned about threats to their internal data systems, but there are external threats to take into account as well. Attackers use skimming devices and other technologies all of the time, which can steal credit card information wherever a credit card is used. After this sensitive information is acquired, attackers can commit credit card fraud wherever they please, which can go undetected until banks or card holders notice suspicious activity related to any compromised accounts.
This is a sort of “death by a thousand cuts” threat for payment providers, as constant small attacks on credit card holders’ information can result in the gradual erosion of customer trust.
DDoS Attacks
Distributed denial of service (DDoS) attacks are a little trickier to deal with, as they can be very powerful and destructive on a systematic level. DDoS attacks are becoming more sophisticated, in that the attackers are finding specific structural weaknesses in internet infrastructure, and then exploiting those weaknesses to bring down large and powerful institutions. Additionally, the expanding internet of things (IoT) makes it much easier for attackers to use internet-connected devices like appliances, TVs, security cameras, and other machines to flood servers with requests, which crashes them.
Typically, only the largest financial institutions are targeted by these attacks. However, hackers are increasingly attacking broader internet structures like the DNS system, which can crash a wide range of businesses’ websites that are using the infrastructure. Fortunately, large attacks such as these have been less frequent, and most payment gateway companies will not have to deal with attacks like these as much. Nevertheless, a downed server poses a threat for payment gateway providers if they’re not able to process transactions in a timely manner.
Safer Transactions
It is important for cyber security professionals, payment gateway providers, and other financial services businesses to continue to develop secure technologies to protect their systems and data. The most promising avenues include advanced encryption, tokenization, and authentication methods, which go a long way towards cutting down on common cyber-attacks. The Payment Card Industry Data Security Standard (PCI DSS) is a powerful industry-wide tool to increase security with, and innovation in this field is welcome as well. Further, proper employee training can go a long way to reduce risk exposure. Ultimately, payment gateway providers and other tech and financial services businesses who innovate in these areas will come out stronger in the future.


Author Bio: Arthur Jones is a consultant for Allied Wallet. He is an innovator in eCommerce services and everything a company needs for success including a global payment gateway system, a prepaid affiliate debit card program, and much more. Arthur has extensive experience in the eCommerce and merchant services industry, and regularly writes about it for interested readers.


IMAGES:

Friday, November 25, 2016

Interchange Plus Benefits and Cost Savings

How Interchange Plus Saves Money When the Markup Becomes Too Expensive

When you have a business, whether it is a retail store, grocery cart or lawncare service, you have to be able to take payments. In today’s world, this means being able to take credit cards easily. Most of your customers are not likely to have cash or even a check on hand to make a payment for products or services. You must be ready to fulfill their need and accept a form of payment that is convenient for them. However, accepting credit cards comes with its own issues, like fees. How do you best handle these fees? Many businesses are finding that interchange plus is a solution to this problem.

What Is Interchange Plus?

Typically, you will have a few options on how your fees will be structured for credit card payments. Common options include bundled or tiered pricing. Interchange plus is another option. With this, you get a pricing structure that allows you to see the components of the costs. It is reported much more clearly and allows you to plan your costs much more easily. It is available for Visa, MasterCard and Discover. 

How Does It Work?

When you process a credit card, the credit card brand will set an interchange rate that you are charged for this transaction. You are also charged a processing fee by the processor. The amount of what you are charged for processing can vary by industry. 

How interchange plus works is it allows you to see the basic processing fees and interchange fees individually instead of bunching them into one basic fee, which is how other methods do it. It allows you to see exactly what you are being charged for every transaction, so you can optimize your credit card related expenses. This is compared to other systems that lump everything together so you do not get to see what is being charged where, so you may never really know what processing or interchange fees you are paying.

What Are the Benefits?

The main benefit here is that it is clearer than other options. You get to see what you are paying in a very easy to understand format. Because you are able to see all the fees, this opens doors to getting lower fees. Companies are more willing to lower costs, which passes the savings onto your business. In addition, you can better choose a processing company because you will know what they are charging you and immediately see the best offer. 

How Do I Find the Best Deal?

The rates you are offered can vary quite a bit. They are based upon many different factors. So, what may be great rates for one business may not be for another. You have to consider things like what industry you are in, how much risk your business poses and your average transaction amounts. There really is no one answer to the question of what is the best deal. The best thing you can do is choose a processing company that has your best interests in mind and who is willing to work with you. They should be open to the idea of interchange plus, too. If a company is used to this method, it will often be very happy to offer you the best possible rates. 


This guest post by Brian Thompson has been provided by our friends at Transaction Services.
Brian Thompson is a business man who means business.  He has helped several companies thrive in the business world, and in his spare time writes for several blogs.
Follow him on Twitter @Biz_Gab

Friday, October 16, 2015

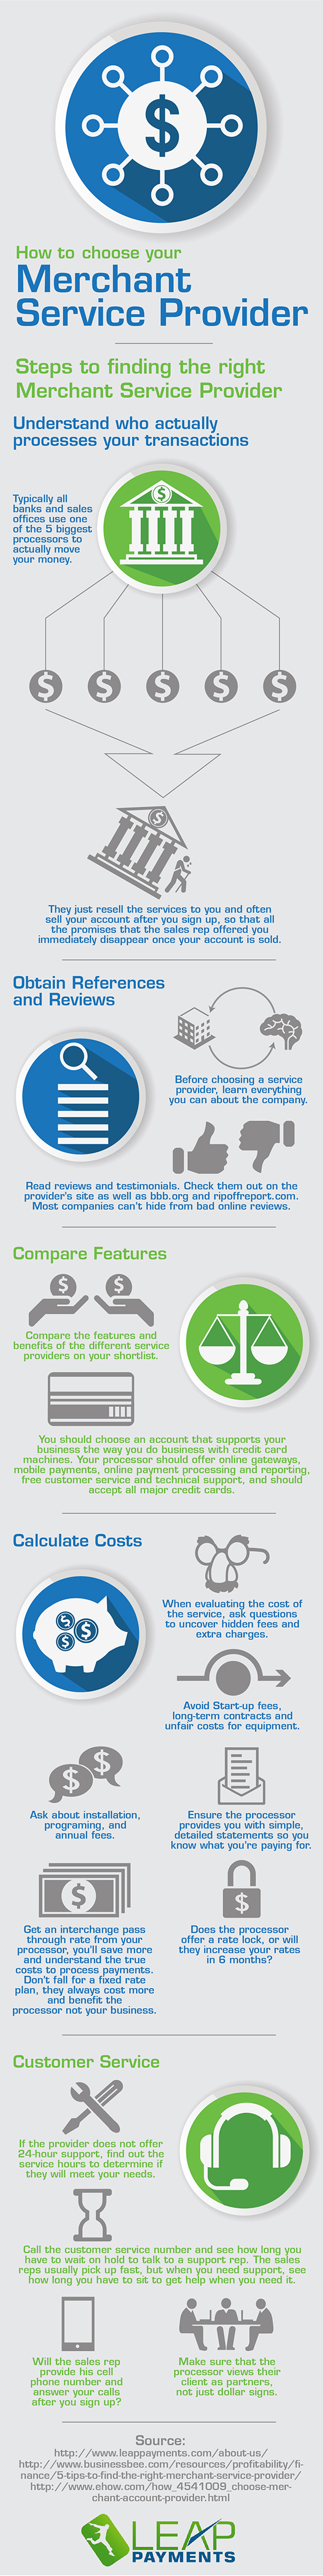
How To Choose Your Merchant Services Provider

Below is an infographic provided by Leappayments.com -- they contacted me a long, long time ago about featuring this on my blog and it managed to get lost in my inbox for quite a while. Every now and again, I would pull it up and look at it and think to myself that, yes, it was a nice infographic.

And since it features information that, for the most part, I have already written about in various posts, I thought this might act as a handy reminder. So, here it is, compliments of Leap Payments, with whom I have no working relationship, and therefore cannot vouch for the company beyond this excellent presentation.

I will caution only one thing with regard to the infographic. It suggests that you pay attention to online reviews, which you should -- but it does not go into detail about how a very small number of rather loud or disgruntled merchants might give very bad reviews of a company that are because of situations where the merchant was at fault. I've read enough such reviews to be able to recognize them, but most merchants and potential agents probably have not. Trusting bad reviews or outstanding reviews blindly is not a good thing -- always look for reviews that give a balanced view of the experience, back up the conclusion with good examples and otherwise tell something more about the company. Neither a few bad reviews nor a few good ones are likely to tell an accurate picture of a company. Additionally, negative reviews (especially on Rip Off Report) are much more common than positive reviews overall, because people having a good experience are less likely to feel the need to write a review in the first place. After all, why would anyone go out of their way to say, "Company X is doing exactly what they are paid to do," which is essentially what every good review would be saying. It's a service, people! Expect it to work properly and be a good value for the money!


Tuesday, October 21, 2014

Update to Harbortouch POS Terms Improves the Best Full POS Deal On the Market

The Harbortouch POS systems have always been a good economic choice for small or medium size businesses that want a fully-featured POS system without having to spend thousands (or tens of thousands) of dollars out of pocket just to get set up. But many merchants have balked at the lengthy five-year agreement required to qualify for the "free" equipment placement. Even though the monthly fee was comparable to the requirements of other system providers who charged for their equipment, nobody likes being locked into a service for an extended period.

Good News for New Harbortouch Accounts


Harbortouch has now begun implementing two significant improvements in their agreements for new POS systems. First, on their lower-end POS, there is an automatic trial period of 30 days. While many companies offer 45 days, which is what you need to ensure that a full statement period is covered, this is still an important announcement from Harbortouch. This way, there is a chance to ensure that all the reports work properly and that all deposits happen as they are supposed to.

The really exciting part, however, is that their Elite II system now comes with only a three year commitment. And this is at the same monthly rate that they charged for the service before. This is a significant potential savings when the hard costs of ownership are considered. Of course, the reality is that most merchants will likely continue with the service and the payments well past the three years, but it is good to know that if cheaper and better technology is available, nothing will prevent a merchant from being able to adopt it.


Wednesday, July 16, 2014

AMEX at the Same Rate as Visa and MasterCard -- Is it True?

Merchants may have been hearing over the past few months that some agents are claiming they can provide American Express transactions at the same low Qualified Rate as swiped Visa and MasterCard transactions. Well, yes and no. It had a lot to do with which network is handling the transactions, at least at the moment, and also what platform the transactions are being processed on.

Let me simplify this a bit. The first thing merchants should know is that only Global Payments affiliated providers are offering this low rate option for AMEX, not First Data network affiliates and probably not Paymentech, either. Merchants with a POS system that requires a First Data connection are currently out of luck unless they change systems. The good news is that merchant services providers like North American Bancard, Total Merchant Services and other processors that use the Global Payments network are already offering the reduced American Express rates to their new clients and rolling them out to existing clients.

For users of mobile "pay as you go" apps like Phone Swipe, PayAnywhere or Square, which use a simple swipe rate for all their card transactions, AMEX is already going through at the lower rate, which is 2.69% for NAB's Phone Swipe or 2.75% for Square. That is already less than most merchants had been paying for AMEX charges. But what of the promised 1.69% (or less) Qualified Rate for merchants on tiered processing?

This is where it gets muddy, but don't worry: it is still a lot cheaper than before. When a merchant has a standard contract and all its monthly fees, they also get much lower rates to offset those fees and, if they are processing over $3,000 each month, ought to see a net savings that improves as volume offsets the monthly fees. Such merchants may have a Qualified credit card rate of anywhere from 1.08% (plus dues and assessments and network fees) on up to around 1.79% or even more, depending on how the account was set up. What is happening now is that American Express is being priced at the same percentage as the other cards, but with a small catch.
The catch is that the other associated charges are slightly higher than the other card brands. Visa, MasterCard and Discover (and also the new PayPal card) all have additional little fees sneakily tacked on and passed through to merchants for things like "brand usage," "network access," "assessments," and more. And these tiny amounts add up. The fact is, each brand of card determines its own fees and to make it possible to sell lower rates, the processing companies take those out of their Qualified Rate and just pass the cost along to the merchant at the end of each statement, all lumped together. This is where merchants will notice that, yes, while their AMEX transactions have the same low rates, they still end up costing slightly more.

The bottom line, though, is that for merchants who take a lot of American Express cards, this new program can lead to a significant savings on the bottom line. Need another bonus? Turns out that the AMEX charges will also post along with the other card brands now, as well, which could be next day or within 48 hours, no longer requiring the additional day or two that American Express sometimes takes to make the deposits. All told, this is a lot of good news for merchants who are set up with the right plan and the right company. 

Consultations are always available, no pressure and no obligation.

Tuesday, July 15, 2014

PayAnywhere Storefront POS-Lite Updates to Version 2.2

The Most Affordable POS System Just Got Upgraded

North American Bancard's PayAnywhere Storefront payment application for Android just got a major tweak. While it still is not a replacement for a full-POS system like Groovv or ShopKeep, it remains a perfect solution for small retail businesses that do not need the system to control the stock of hundreds of inventory items, maintain open checks or log employee hours. PayAnywhere Storefront still allows the input of inventory items for quick checkout (it just doesn't keep track of what is in stock) and offers a wide array of sales reports. But mostly it offers one of the most cost-effective checkout systems for merchants who want to keep low rates and low fees while still tapping into the most-wanted features of the higher-priced systems and taking advantage of added mobility.

New Features in PayAnywhere Storefront 2.2

  • Faster checkout! Merchants no longer have to press an extra button before swiping -- just run the card through the card reader and get that transaction going. There is also a novel new feature to

Thursday, July 10, 2014

Affordable Tablet POS Systems That Support Open Checks and Tips from Groovv and ShopKeep POS

Android and iOS based POS Systems perfect for small and mid-size restaurants, coffee shops, bars or any business that accepts tips or open tabs.

Most mobile credit card processing solutions are not able to handle tips or open checks (tabs) at all, acting strictly as the equivalent of a counter-top terminal for swiping or key-entering a single transaction. This works well enough for most people, who rarely will need modifiers of any sort. However, business owners wishing to move away from or avoid altogether the high-priced POS systems now are seeing viable options appear in the affordable tablet-based solutions entering the market.

While affordable solutions such as Harbortouch have begun presenting themselves in the market for full POS systems required for high-inventory merchants who need extensive employee tracking and reporting for the accountant, the mobile marketplace has seen an explosion recently with excellent retail solutions like

Sunday, April 6, 2014

Time Again for Increases in Interchange Costs

April Interchange Increases

It happens at least twice each year: the credit card processing companies all send out notices regarding unavoidable pricing increases for their merchants. Like clockwork, April brings the news, usually overlooked by merchants who are used to glancing past the fine print on their monthly statements (if they read them at all). In case you missed it, here is a brief rundown of some current increases in interchange cost associated with the major credit card brands.

Not surprisingly, processing companies use this excuse to cry poor, and in addition to merely passing the additional costs on to merchants, they will mostly tack on across the board increases to compensate for the new expenses while also generating more income.

Monday, March 10, 2014

New PayAnywhere (Free) Tablet Storefront Solution Is Here

First the good news: North American Bancard (NAB) has a new PayAnywhere branded mobile tablet-based processing program which offers the placement of a free counter-top system and some great new options built around a 10 inch Android tablet (plus an additional mobile card reader for phones or tablets). It is one of the most affordable processing solutions on the market that takes advantage of mobile solutions at highly competitive rates with a future-ready, upgradable combination of hardware and software. It will become EMV compliant and is consistently being updated on the software side to take advantage of the latest technology while offering more enhancements to merchants. The program is very similar to the previous Phone Swipe Tablet Program which NAB been providing, but without the high volume requirements.

Processing of Visa, MasterCard, Discover, American Express and the new PayPal card are all available with Next Day Funding and a lower swiped rate than Square or any "Pay As You Go" style programs, and still without additional transaction fees.

Having stated the good news, you might expect that there is bad news to counter it. But there isn't, at least not in the sense of anything new about the processing industry. Instead, there is the caveat that merchants still must deal with the same basic pricing and service of typical merchant accounts, including the PCI responsibilities and standard fees. Moreover, however, this program is not a "one size fits all" solution. If merchants are not processing over $5,000 in monthly charges, there is a good chance this program is not for them. On the other hand, it could save the right merchants a lot of money, offer a forward-thinking alternative to standard terminals and increase both productivity and profits. All will be revealed after the jump...

Friday, January 3, 2014

New Phone Swipe Promo, What It Really Means

North American Bancard just released a new promotional push for its Phone Swipe product, touting it as a new, first of its kind deal for 2014. The text of the promo reads:    

"This January, be the first in the industry to offer Visa, MasterCard, Discover and even AMEX at 2.69% with next day funding to all pay-as-you-go customers! It's just another reason why Phone Swipe is the mobile payments solution that sells itself!"  

Since the next day funding option has been standard for new accounts since mid-2013, and since American Express cards have been processing on Pay-As-You-Go accounts at the same qualified rate as Visa, MasterCard and Discover for the same period, I wanted to find out which part of this was supposed to be new for the new year. Well, it turns out that it isn't new and nothing has actually changed in the program. The spin is simply the suggestion that agents should take time now - in January - to point out that Phone Swipe is the first processor to offer qualified charges for the main card carriers at this rate. Agents and merchants should still be aware that the same mid/non-qualified downgrade of 80 basis points continues to apply to all accounts on the Pay-As-You-Go plan, along with the $0.19 transaction fee for business signature cards and even rewards cards.

Does this make the Phone Swipe program a bad deal?


If you have read this blog before, you know that I have endorsed Phone Swipe for a long time. I even

Monday, November 4, 2013

October 2013 Interchange Adjustments

October is typically a month when new pricing adjustments occur in the merchant processing business. The credit and debit card brands, specifically Visa, MasterCard and Discover, make adjustments to their pricing structures and/or services. Once this occurs, the merchant processing companies then generally restructure some of their pricing to prevent profit loss, spread out new costs or otherwise either stay competitive or profitable. Some account managers will choose to absorb certain costs or prevent some merchants from seeing increases in their billing, however it is also possible that some of these posted increases will be used as an excuse to increase fees across the board and not simply for the actual items affected. For this reason, it is always important to read the fine print, or at least the monthly announcements on each processing statement.

Here is a quick breakdown of the recent changes from October, 2013, effective from the beginning of the month. The changes may look small at first, but remember that these tiny amounts add up when they are per transaction. For the card issuing companies, this can mean a huge increase in revenue (although, to be fair, theoretically the increases are designed to deal with corresponding costs already being incurred).

The New Costs

All Discover transactions now have

Monday, September 30, 2013

PCI DSS 3.0: The end of store and forward on mobile?

It is time for new PCI changes to get implemented. Last February (2013), the PCI Security Standards Council released a document on mobile payment security guidelines. While it is not the most entertaining read in the history of guidelines, it does shed light on some of the changes we are going to see implemented in the industry over the coming year. In November, expect to see a new set of regulations being handed down, to be fully implemented by the star of 2014. But most processors, not wanting to find themselves caught in the awkwardness of being out of compliance when the date hits, attempt to get on the bandwagon as early as possible and will demand the same of their merchants.

Sunday, September 22, 2013

PCI Program Update for North American Bancard Merchants

A notice came out today, September 17th, 2013, from the folks over at North American Bancard, which also provides the Phone Swipe and PayAnywhere products in the mobile processing field. Merchants who are on the mobile "Pay As You Go" plan (also known as Option B for Phone Swipe) should note that this information will not apply directly to their accounts, since those types of accounts have the compliance fees rolled into their higher percentage along with all other incidental costs (which is why Phone Swipe may be so much more cost-effective for merchants who do under $2,500 per month).

Here is an excerpt from the NAB correspondance:

"The monthly fee for PCI non-compliant merchants will be increasing from $6.95 to $14.95. This increase is effective for Global merchants and for First Data merchants. Your merchants will continue to receive messages on their statements notifying them when PCI billing will occur.

Note that the annual PCI compliance-related fees will not be increasing. Those fees will remain the same as they have for the past three years: $79 for all main accounts ($99 if non-compliant) and $19.95 for each additional account with the same Tax ID number and/or same Principal/Social Security Number ($24.95 if non-compliant). We are proud to say that these annual fees continue to be lower than those of our top competitors despite the fact that our compliance programs offer significantly better levels of protection and that our costs for the programs continue to increase."

NAB, just like most payment processors, sends their merchants notices regarding Payment Card Industry security standards and compliance issues in the merchants' monthly processing statements. Frequently merchants forget to check their statements for these announcements, which may also include rate or fee increases due to higher percentages being charged by Visa, MasterCard or Discover, that the processor might pass along to the merchant. It is essential that merchants remember to check their monthly statements, not only to verify that they are not being overcharged or billed for something that they do not understand, but to ensure that they are up to date on any changes or responsibilities regarding their accounts.

Wednesday, July 31, 2013

Harbortouch "Free" POS System Program, Simplified

I recently had the opportunity to expand my consulting service with the products offered by Harbortouch, aka United Bank Card, Inc. (UBC). UBC is a very similar company to the other processors I use, in terms of size and offerings and the flexibility of pricing, so there was little incentive for me to go through the paperwork until I looked deeper into their Point of Sale terminal program. As it happened, I had a client who was looking for a POS system and we decided to do some number crunching and some feature comparisons. What we found surprised me.   


My first impression was that the Harbortouch program would probably fall into the "too good to be true" category. Everyone who has been around the block knows that "free" terminals generally means that you get to borrow the equipment if your pricing structure is high enough. That's fine for most businesses, because the minimum pricing requirements to qualify for equipment placement are usually offset by the savings of not having to purchase new equipment combined with the ability to exchange a defective or outdated machine at little or no cost. The one thing that often does get merchants with equipment placement is that they are likely (but not always) locked into a 3-year term with a cancellation fee that is higher than the price of a terminal. But here we are talking about standard counter-top card swiping terminals and nothing beyond that. When moving into POS territory, things become a bit more complicated. And, in this case, more enticing.

Thursday, May 16, 2013

Phone Swipe Tablet Placement Program Update

What It Is

The new Phone Swipe processing plan from North American Bancard offers a free tablet for merchants to use and lower rates than "Pay-As-You-Go" plans, or even most monthly processing plans.

A customized iPad running the updated Phone Swipe POS Solution

Who It's For

The merchant requirements for this new processing program ("Option C") are a little steeper than in  the standard Phone Swipe programs. For "Option A," which has a $14.95 monthly cost but a wide range of structures customized by the agent for each merchant, the only real minimum is that the merchant processes over $2,000 each month (and really should tend toward $2,500 and up), because that is where it becomes cost-effective. For "Option B," commonly known as the "Pay-As-You-Go" plan, there are very few requirements at all. 

In order to process with the "Option C" plan, however, merchants need to be processing over $10,000 every month and also must have a processing history to show this. At least the most recent month's statement will be required to submit to the underwriting department after the application is sent in (via a secure web form filled out by the merchant after receiving an email from the agent who is setting it up). 


What's the Catch?


Thursday, April 18, 2013

Recommended Solutions


One Size Does Not Fit All

One of the most important things for merchants to remember is that what works best for one business may not be a good fit for another. This applies in almost every area of business, and the processing set up for a business is no different. Except in one way: every merchant wants the cheapest solution that will serve their needs.

The problem is, what saves one merchant money may not save another merchant who does business very differently. Having the lowest transaction fees is terrific until it means that all transactions are going to have to be stored for later because a merchant is trying to save on mobile processing fees, only to discover that more charges are downgraded and other charges are simply not approved... In fact, there are dozens of considerations to be made before ensuring that the merchant has the best program set up.

Some generalizations remain true

It is always in the best interest of a merchant to save money. The rates and fees set by Visa, MasterCard, Discover, American Express, et al,  are varied by card type and transaction type, and even have built in adjustments by industry. There are ways in which the processing companies have worked to save merchants on some types of charges while profiting off other types of charges. This was the birth of "Tiered" pricing.

A good "Tiered" deal may actually save a merchant money over an Interchange-based plan. This may be the case when the Mid- and Non-Qualified markups are not excessively high and the Qualified rate itself is low, because many cards may be processed at very little profit or even at a loss for the processing company, versus the consistent markup on every charge as processed via an Interchange-plus agreement. These kinds of "Tiered" plans are pretty rare, however, and many merchants find that their "Tiered" rates are raised periodically to compensate for the increase in Interchange costs for a few card types every six months or so. This is also assuming that the Interchange-plus plan is based on the typical "book rates" from most processors (likely 50 basis points over cost).

I generally believe that Interchange-based plans are the most fair-minded and often the most cost-effective. There is no undue rounding up on rates, no downgrading. And there is usually no additional transaction fee to go along with the downgrades, either. A merchant pays the cost of processing with a nominal surcharge on the total and a reasonable fee per transaction. This "cuts the fat" and makes the costs much more equitable most of the time. Still, this sort of plan sometimes looks complicated and does not work best for every merchant, so the pros and cons must be examined.

Recommended Solutions

I like to put my merchant clients into a narrow range of solutions whenever possible. For some, they have an existing POS system that needs to be reprogrammed and it is as simple as discovering what processing company will interface best with the POS system and then setting an account up with the proper parameters and lowest available cost. I'll use the First Data network for most POS systems, because I can provide that through a third party at much less than First Data usually charges merchants who have accounts directly set up through their processing wing. Plus, I'll do it with no long-term contracts and without cancellation fees. I can also process over the Global Payments network, or through a gateway like Authorize.net. For most high volume businesses, this sort of solution is perfect for them. They have the hardware already, I'll simply provide them with better numbers. I'm not precisely in the POS business, but I have the ability to set up several types of systems and can provide a limited range of them as well.

Tuesday, January 29, 2013

PhoneSwipe Just Got Better

This is just a quick update for those interested in the fast-paced world of mobile processing. As we all know, SquareUp is in bed with Starbucks now. The little white cube is becoming more and more ubiquitous. SquareUp's goal is to make smartphones the new wallet, something that Google also has its eye on and even PayPal has jumped into the game. But what about just getting the best rates for a mobile solution, without the additional motive of sticking your customers with a singular means of paying that only a select few merchants can accept?

Stripping away the branding and the nifty (if unnecessary for the most part) bells and whistles, you are left with a small group of needs. Merchants want low rates and they often want a modest POS system to make transactions easier. While Square does offer a nice version of their software for the iPad, and now some iffy flat monthly rates that might save a small business some money (in a rather narrow window, if you ask me), the recent upgrades in the PhoneSwipe service offered through North American Bancard seem to make it a much more obvious choice for a wider range of businesses.

Lets look at the updated terms rolled out this month.

Monday, September 24, 2012

Next Day Funding: What It Means and When It's Necessary (Or Not)


Every now and again I discuss "next day funding" with a merchant in the course of a consultation. It's something I generally don't offer and few merchants ever mention, but once in a rare while it is a sticking point that the merchant holds as an important aspect of the service.

Case in point, I was chatting with a merchant this morning who must pre-order and pre-pay for product that she sells a "parties" set up in people's homes as sales events. Because she does not keep much inventory on hand until she has an idea about how much she is likely to sell, she is often out of pocket when she begins a sales event and needs to immediately recoup her expenses in order to pay her bills before it becomes an additional expense that cuts into her profits. Because of this, she is essentially attempting to pay her balance before it becomes due, to presumably somewhat mixed results.

Tuesday, September 18, 2012

Why a Merchant Should Never Pay Over 4% in Total Processing Costs

How to spot a bad processing deal 101

It's true: I've spoken with merchants who thought that they were paying a fair price on their processing service even though the aggregate total they were spending for a month of processing was coming out in the range of 5 to 7%. That's right, because they had been with the same service for years and it was provided by a "reputable" company (or even their own bank), these merchants assumed that they were paying market rates and not getting ripped off. But they were wrong.

One of my clients, a plumber, had been paying over 7% when the "discount" rates and transaction fees and monthly fees had all been added together. When he told me this I responded that I was sure he must be mistaken, that no legitimate company should be setting him up at rates that high for his business. But there were his statements, clear as day, and he had been with this same processor for over a decade, just handing the company his hard-earned cash.

All a merchant has to do is check their bottom line. If your total costs to process exceed 4% for any given month and you swipe cards in a retail environment, you have a bad processing deal. Period. Go ahead and figure in the cost of PCI compliance, too. If you're still over 4%, there is a better option on the market. Even if a merchant is primarily processing keyed-in transactions via the Internet, phone or mail order, the total costs should normally be under 4% as well. (Because of some additional costs to process through gateways or shopping carts online, those expenses may need to be removed from this discussion. However, many businesses do spend much more than necessary on gateway fees, so those ought to be examined carefully as part of the bottom line.)

Thursday, August 16, 2012

Cash Advances for Merchants

"Merchant Services" are generally understood to center around the processing of payment data from bank cards or gift cards and the like. There is another aspect to these services, however, that some businesses benefit from in ways that can quickly help them expand, cover shortfalls or otherwise access needed resources without having to go through a lengthy process or get tied into bank loans or mortgages.

By getting a cash advance from their processing company, merchants are able to put funds directly into their bank account and have the balance automatically paid off over a short period of time simply by automatically deducting a percentage of the credit card sales made by the merchant's customers (or, to look at it another way, to pay a higher percentage on sales to cover the repayment of the advance).

An advance program can be used to purchase additional inventory, do necessary repairs or upgrades, or simply pay some bills. Funds can be delivered usually within 5-10 business days. Sometimes even in as little as 72 hours.

This is good for merchants who need the money quickly, those with little collateral or if they have limited access to other areas to get the funds. 

In order to get access to this type of funding, a merchant will generally have to work with a sales agent from the processing company they use. These cash advance programs are great for sales agents, because they generally will share in the profits made on interest, get a nice upfront bonus from the processing company, or both.